Downs Law Firm Laurel, MD

Young Adults and College Planning

November 1, 2023 No Comments

Find Us Online

Building wealth is only half the job. Protecting wealth for your loved ones and yourself is equally important. Through estate planning, business planning, and asset protection, our firm will help you protect everything you love — family, friends, and favorite charities. For more information, visit our website, where you can access our blog, events schedule, and a complimentary newsletter subscription!

College and Estate Planning

College and estate planning intersect at several points that should be considered when planning for the future. When applications and essays are due, let’s talk about some consequences of the college transition to the family.

Planning for College Costs

Opening and funding a 529 College Savings Account to benefit a child or grandchild helps family members invest tax-free for educational expenses. Each state has its own plan. If you invest incollege student your own state’s plan, you may get a healthy deduction on state income taxes. In addition, funds in the account grow tax-free, and there are no taxes on capital gains. For grandparents, funding a 529 account is an excellent way to help pay qualified education costs, while reducing their taxable estate. However, there are limits to contributions, which vary from state to state.
Another means of funding a family member’s educational expenses while reducing the taxable estate is for grandparents to pay for tuition and other qualified expenses. These payments must be made directly to the educational institution to qualify for an exception to the annual gift exclusion limit of $17,000.

Estate Planning for Young Adults

Preparing young adults for the future includes planning for the unexpected. Once young adults become of legal age under state law, their parents lose legal authority to be involved in the children’s financial or legal matters. Parents do not automatically inherit a child’s estate, so those who have inherited family wealth or are entrepreneurially minded may have enough assets to warrant having a last will.

Once their children are legally adults, parents also lose legal authority to be involved in their children’s health care, even in an emergency. Parents may not speak with doctors of their children, access their medical or health insurance records, or make health care decisions if a young adult child is incapacitated. This may seem shocking, but it’s the law. Physicians and hospital systems today don’t have the flexibility to bend the rules as they may have done in the past.

Parents and their young adult children can prepare for worst-case scenarios with several estate planning documents: General Durable Power of Attorney, Healthcare Power of Attorney, LivingDNR Will, and HIPAA form.
A General Durable Power of Attorney allows another person to manage finances. The Health Care Power of Attorney allows another person to discuss medical care and be involved in decision-making. HIPAA forms are needed to permit another person to access health care and insurance records.

An 18-year-old seems like the last person needing a Living Will. However, it is necessary. A Living Will is used to give directions about the kind of care they would want if they had a terminal illness or were critically injured in an accident and unable to convey end-of-life wishes. The Living Will should be specific, especially relating to CPR, resuscitation, the use of a ventilator, or the use of a feeding tube.

Most young adults aren’t thinking about final wishes or handing over the ability to manage their finances. However, these documents are still just as necessary for a newly minted-adult as for a senior. They provide peace of mind, make difficult situations more manageable, and are an emblem of maturity—planning for the future, whatever it may bring.
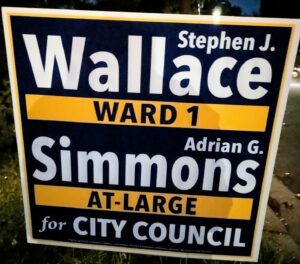
Another Prospect: Our City of Laurel Elections  are on November 7th
If you are within the City of Laurel, please vote for my associate attorney, Stephen J. Wallace, for Ward One, and my Accountant, Adrian Simmons, who is also running for an At-Large Seat on the City Council.
They are both honest, smart, and hard-working men with families and business interests. They will work hard for Laurel.

Copyright © Integrity Marketing Solutions. All Rights Reserved.
Multiple Marriages and Blended Families Create Unique Situations

September 13, 2023 No Comments

Find Us Online

Building wealth is only half the job. Protecting wealth for your loved ones and yourself is equally important. Through estate planning, business planning, and asset protection, our firm will help you protect everything you love — family, friends, and favorite charities. For more information be sure to visit our website where you will have access to our blog, events schedule, and a complimentary newsletter subscription!

Multiple Marriages and Blended Families Create Unique Situations

Planning for incapacity and death in a blended family requires a more complex approach than for traditional families. By its very nature, the blended family has more fault lines. As parents and stepparents age, planning needs to take this fact of modern life into consideration.

Clarifying Roles and Making Decisions About Responsibilities

Roles and responsibilities should ideally be assigned in advance based on skills and availability. This is not the time to make up for past slights. All of the stepsiblings should be considered in light of their abilities to manage finances, follow instructions for health care decisions,caregiving grandparents and communicate with all step-siblings. The nature and quality of the relationships should be considered in weighing out responsibilities. Dividing along biological lines may not be the right solution. This needs to be discussed and resolved.
Someone needs to be appointed as the primary decision-maker (known as an agent or attorney in fact) under a health care power of attorney (or proxy) and a financial power of attorney. If a revocable living trust is created, someone will be named to serve as a trustee. Commonly, the person appointed as trustee also serves as an executor under a last will and testament. All children need to know their tasks and who has been chosen for which role. Appointing successors for each of these roles is a smart and practical move.

Incapacity Can Be More Challenging than Death

If one spouse becomes incapacitated, usually the healthy spouse steps in to make medical decisions, manage finances, provide care for the spouse, and run the household. If the relationship with stepchildren is good, the well spouse may be able to continue as the primary family contact.

Unfortunately, the family dynamic deteriorates in many cases when one parent becomes incapacitated. The well spouse may attempt to limit children’s access to visit their ailing parent, claiming their parent is not well enough to see them. Assets may be moved to hide them from biological children. If Medicaid planning is done without any involvement from the children, it may appear that assets are being secreted away. Communication between aging parents and stepsiblings needs to address these issues in advance, especially if there are issues within the family.

Managing Expectations for Inheritances

To avoid children being disinherited, trusts can be structured to distribute wealth in a deliberate manner. One strategy is to place assets in a trust for the surviving spouse, so when the second spouse passes, assets will be transferred either to an individual trust for each of the stepsiblings or directly to the stepsiblings as beneficiaries. If all assets from the first spouse pass to the surviving spouse, there is no means of protecting the assets for the biological children of the first spouse and litigation may ensue.

Family Meetings with Professional Advisors

To avoid the potential issues described above, a series of family meetings where all parents and all stepsiblings are present should be scheduled. Video meetings allow everyone to be included, regardless of where they live. Incapacity planning, finances, end-of-life wishes, andcaring family hold hands together at table even funeral arrangements should all be discussed. Expectations should be set for inheritances now—it is best for stepsiblings to know what the future holds to eliminate surprises.
Distributing Personal Items to Prevent Family Fights

The biggest fights are often over sentimental items with the least value. To preclude post-mortem quarrels at a time when emotions are running high, a written memorandum disposing of tangible personal property (whether a ceramic frog collection or an heirloom Civil War sword) can be written to clarify which items should pass to which child. The laws of most states provide for this approach, especially when the memorandum is incorporated by reference in a last will and testament. Appointing a fair-minded person who can handle some stress is the key.

In explaining the decisions may be helpful to keep arguments at a minimum. Alternatively, some parents give sentimental items away while they live, gifting with warm hands. Both the giver and the recipient can share the sense of passing family belongings to the next generation.

© Integrity Marketing Solutions. All Rights Reserved.

Maryland’s New Law: Inheritance Tax Exemption for Domestic Partners

August 14, 2023 No Comments

If you know a couple that is living together in a committed relationship and are not married, there is a significant change in Maryland Law that could save them many thousands of dollars.cognative decline

Maryland has an inheritance tax of 10% if you leave property to people who are not close relatives. Exempted from that tax are spouses, descendants, parents, grandparents, and brothers and sisters. Among the people who pay 10% are “Domestic Partners:” people who live together in a committed relationship but are not married. As Maryland does not recognize common law marriage, a long-time “Significant other” pays a 10% tax.

One exemption to this tax is for jointly owned real estate of a Domestic Partner.

“Domestic partnership” is defined according to the definition of the term under the Health-General Article (relating to hospital visitation and medical emergencies). “Domestic partnership” is a relationship between two individuals who (1) are at least 18 years old; (2) are not related to each other by blood or marriage within four degrees of consanguinity under civil law rule; (3) are not married or in a civil union or domestic partnership with another individual; and (4) agree to be in a relationship of mutual interdependence in which each individual contributes to the maintenance and support of the other individual and the relationship, even if both individuals are not required to contribute equally to the relationship.

Several years ago, I had a client who was terminally ill. He was leaving his “Significant other” over $600,000 from his retirement plan. I told her of the tax she would need to pay. He discussed the possibility of marriage. He said he talked to his CPA, who assured him there was no such tax.

CPAs generally don’t work on inheritance tax issues and the CPA was wrong. When my client died, the inheritance taxes exceeded $60,000.

NEW MARYLAND LAW

Maryland has a new law taking effect October 1, 2023, that exempts from inheritance taxes all tax property owned by domestic partners if the Couple files a Domestic Partner Certification with the register of wills and it is acceptedestate planning during divorce. Although the forms are not yet in, the register of wills has presented a basic overview.
Parity with “Marriage” and “Spouse”
The bill alters various definitions and provisions in the Estates and Trusts Article so that, in many cases, a “registered domestic partnership,” and a “registered domestic partner” are treated the same as a marriage, and a spouse, respectively. In the following statutory provisions of the Estates and Trusts Article, the bill adds “registered domestic partnership” where the term marriage appears, and adds “registered domestic partners” where the term spouse appears:

  •  definition of a child;
  • provisions related to intestate succession, including share of the surviving spouse, division among surviving issue, distribution when there is no surviving issue, and inheritance from a person born to or conceived by individuals who are not married;
  •  family allowance; and
  •  order of priority for letters of administration, appointing a successor personal representative, or appointing a special administrator, as specified.W

While you may not be living with someone you are not married to in a romantic relationship, you likely know someone who is cohabitating. If you do, I strongly suggest that you pass this newsletter on to them and recommend that they see an estate planning attorney as soon as possible. You could save a friend many thousands of dollars with this important information.

Conclusion:

The new law in Maryland regarding domestic partners and inheritance tax represents a significant step towards achieving equality, recognition, and financial security for domestic partners in Maryland. By providing the same inheritance tax exemptions as married couples, Maryland recognizes the value and validity of domestic partnerships and aims to eliminate disparities in tax burdens.


Great Planning Begins at Home

July 9, 2023 No Comments

Find Us Online

Building wealth is only half the job. Protecting wealth for your loved ones and yourself is equally important. Through estate planning, business planning, and asset protection, our firm will help you save everything you love — family, friends, and favorite charities. For more information, be sure to visit our website, where you will have access to our blog, events schedule, and a complimentary newsletter subscription!

Excellent Planning Begins at Home

It has been said that your home is your castle, and your home is where the heart is. Without a doubt, the place we call “home” is exceptional. This is especially true if your family is grown and gone. Can you hear laughter in the walls from birthdays, holiday celebrations, or graduationdownsize gatherings? Intermingled with the joy, there may be some sorrow in those walls, too.
Yes, home is an extraordinary place.

In addition to the memories that reside inside, your home likely holds a significant amount of your wealth. Consequently, you must ensure your home is protected while you live there. When you are ready to leave your home, there are some essential things to know about selling your home or even transferring it to your loved ones.

In this article, we will survey some fundamentals to help you avoid some common legal and tax mistakes when it comes to your home, along with some thoughts on transferring it successfully.

Insurance and State Law Protections

The purpose of homeowners insurance is obvious – you pay an insurance premium you can afford now to cover a loss you cannot afford later. Such insurance is prudent and necessary whether it is a fire, flood, twister, or other disaster. Mortgage companies require homeowners to maintain homeowners insurance as a condition of the mortgage. In addition to at least a basic homeowners policy, ask your insurance agent about an “umbrella” policy to provide additional coverage above your policy limits. This added protection is relatively inexpensive but can protect your home and other assets if you are sued. All it takes is one “slip and fall” by an invited (or uninvited) guest on your property for the policy to pay for itself many times over.

All states afford some degree of legal protection for your home itself should you be sued or file for bankruptcy. Some states protect a specificCustomized estate plan dollar value, others may protect the homestead to varying degrees depending on how long you have lived in your home, and still, others may provide complete protection to married couples when they jointly own the home as tenants by the entirety. In the end, state law will control when it comes to the degree of protection afforded your home ownership. An experienced estate planning attorney can explain the protection unique to the laws of your state.
Joint Ownership Dangers

Most married couples own their home together, reflected right on the deed to their home. If held as “joint tenants with rights of survivorship” or as “tenants by the entirety” and not as “tenants in common,” then no “probate” is required for the “surviving spouse” to “inherit” complete ownership of the home.

When that happens, do not make the typical “mistake” of adding the name of an adult child or other family member as a new “joint tenant” of your home to avoid future probate at your passing. This single mistake can have many severe tax and non-tax consequences, including:

  • Lossing tax advantage by gifting your home to a child during your lifetime;
  • Subjecting your home to the liabilities of your joint tenant (e.g., divorces, lawsuits, or bankruptcies); and
  • Penalizing you for Medicaid eligibility purposes.

Gift versus Inheritance

When you gift your home by transferring full ownership to a loved one during your lifetime by deed, you are also making a future gift to the IRS in the form of additional capital gains taxes when the home is sold. That is because you are giving your loved ones your basis in the house and the home. On the other hand, if they “inherit” the home from you, then the basis they inherit is the home’s fair market value as of your date of death. This one move can make a big tax difference.

Wills, Deeds, and Living Trusts

There are a variety of ways to transfer your home at your death. One method is to do nothing and let the probate court distribute your home according to state law. This method may not reflect your wishes and can be expensive and time-consuming. A last will can enable you to control who inherits your home and authorize the most streamlined probate process permitted in your state. This can save considerable expenses and delays.

If you want to bypass probate, consult a qualified estate planning attorney to determine whether your state provides for non-probate real estate transfers. About 30 states provide for “beneficiary deeds” to transfer your home without probate upon your death. These deeds areSpendthrift trust revocable and amendable by you during your lifetime, too.
Revocable living trusts are a popular method to avoid probate on your home and other assets. You create the trust, name yourself as trustee, and are the beneficiary throughout your lifetime. If you become incapacitated, a successor you appoint takes over … but you remain the beneficiary. At your death, the trustee administers and distributes the trust assets according to your instructions.

All wills and deeds are a matter of public record. If “privacy” is essential to you, you may want to consider using a revocable living trust to transfer your home and other assets.

Exploring your options about how to pass your house on to your loved ones is a great place to start planning your estate. We have here to help guide the process and encourage completion when you are ready to start. We can also revisit the decisions you have put in place already.

Some updates about us

We at the Downs Law Firm now have four attorneys to help with the process. In addition to founder Tom Downs, we now have Stephen Wallace, Justin Wedgewood, and Patricia Peréz. They work with our team of experienced legal assistants to provide help as needed.

Copyright © Integrity Marketing Solutions. All Rights Reserved.

“Testate” Probate Versus “Intestate” Probate

June 12, 2023 No Comments

Find Us Online

Building wealth is only half the job. Protecting wealth for your loved ones and yourself is equally important. Through estate planning, business planning, and asset protection, our firm will help you protect everything you love — family, friends, and favorite charities. For more information, be sure to visit our website, where you will have access to our blog, events schedule, and a complimentary newsletter subscription!

“Testate” Probate Versus “Intestate” Probate

Asset distribution is a central task of both “testate” probate and “intestate” probate. A testate probate is available when the decedent dies executing a valid last will and testament. Conversely, an “intestate” (Without a Will) probate is the default when the decedent dies without aWill contest valid last will and testament.

In most states, probate is required when someone dies, leaving an asset or assets not titled to a trust or for which there is no surviving joint owner or without a designated beneficiary. Consider such assets “orphaned,” with no living owner. Consequently, probate is required in the state where the decedent was last a resident to find a new owner for any orphaned assets left behind.

How does “testate” probate work?

First, a petition is filed with the local Register of Wills, which is found in Prince George’s County, Montgomery County, or any other Maryland County. The Register’s office reviews the last will and testament to ensure that it is the “last will” and testament and that it satisfies the particulars required under state law to be valid. Once the Register accepts the document as a will, the local Orphan’s Court issues a “Letter of Administration” to the personal representative appointed under the last will. This document empowers that person, also called the executor, to begin paying just debts, taxes, and expenses of the estate and, ultimately, to distribute and manage assets according to the terms of the last will.

Once filed with the probate court, the last will and testament and related documents become part of the public record. Anyone can request and view these documents, including creditors, salespeople, and even thieves. This is why vulnerable surviving spouses are contacted by third parties promoting their professional (and less than professional) services. Scammers also use court documents to identify potential victims.

Probate also requires the executor to notify people named in the last will and lawful heirs not named in the last will. Each of these parties is also provided a copy of the last will. Consequently, state probate statutes provide for some time for disgruntled heirs to challenge the last will.

What happens if a person does not have a will but they do have an estate?

Without a last will, “orphaned” assets still require probate before distribution. With no last will appointing an executor chosen by the decedent, State Law, called “Intestate Succession,” applies, and the Register of Wills or probate court appoints an estate administrator toassets in an estate

fulfill that function. This person may be a professional administrator who never knew the decedent or the family of the decedent. There is no requirement for the probate court to appoint a family member to serve as the trust administrator.

The estate administrator follows the state laws of intestate succession.

The administrator of an “intestate” estate has the same responsibilities as the executor in a “testate” estate. However, since the decedent did not create a last will to provide instructions regarding the estate distribution, the intestate estate passes according to state law. In most states, this one-size-fits-all distribution formula is based on the degree of kinship to the decedent. If a surviving spouse has no children, the spouse may inherit everything. If there is a surviving spouse and children, then the spouse and children share the inheritance.

Failing to have a last will leave the family open to many challenges.

Without a last will, the family has no control over how assets are distributed. A professional administrator will need to be paid for their services. If the estate is small, this will decrease any potential inheritance. A last will is also used to name guardians for minor children. Therefore, if there is no last will and no surviving spouse, minor children will be assigned a foster family until long-term placement can be

unequal is fair
Conflict.

made.

What if you want to avoid probate over your assets completely? Consider creating a fully-funded revocable living trust with a trustee of your own choosing to manage the trust assets privately and confidentially for your beneficiaries. An experienced estate planning attorney can help you select the right estate plan for your unique circumstances now and keep it up to date since changes inevitably occur.

I know we are preaching to the choir to a great extent, as you have an estate plan with our firm. This is given with the hope that you may inspire other family members or friends to take the same prudent steps that lead to a well-thought-out end of life. If we can be of help, we would be glad to assist.

Copyright © Integrity Marketing Solutions. All Rights Reserved.

The Benefits of Beneficiaries

May 14, 2023 No Comments

Find Us Online

Building wealth is only half the job. Protecting wealth for your loved ones and yourself is equally important. Through estate planning, business planning, and asset protection, our firm will help you save everything you love — family, friends, and favorite charities. For more information, be sure to visit our website where you will have access to our blog, events schedule, and a complimentary newsletter subscription!

The Benefits of Beneficiaries

What is a Beneficiary?

Just like the word suggests, a “beneficiary” is a person or entity receiving the benefit of an asset. A beneficiary can be a spouse, child, grandchild, or really anyone. In addition, a beneficiary does not need to be flesh and blood. For example, your favorite charity can be aAnnuity beneficiary beneficiary. If giving to a charity is a significant part of your estate plan, directing IRA or 401K benefits to the charity makes sense, as they don’t pay income taxes. One beneficiary everyone wants to avoid, however, is the IRS!
How is a Beneficiary Created?

A beneficiary is designated when the person or legal entity is named in a legal document to inherit specific assets or assets, generally upon the owner’s death. These legal documents are commonly a last will and testament or a revocable living trust. Assets can alternatively pass directly independent of any such legal documents. Certain assets pass by contract through beneficiary designations, like those provided for life insurance death benefits or the proceeds from a retirement plan like a 401(k), 403(b), or IRA. The non-probate transfer laws of many states allow assets to pass directly to a beneficiary by a designation applied to the asset itself, whether paid on death or transferred on death. Other assets pass by operation of law to a beneficiary, like when a joint owner of an asset dies and there is a surviving joint owner.

Who Can Be a Beneficiary?

Minors may not be direct beneficiaries. If the intention is to provide financial support for the minor, an “inheritance trust” can be created to administer and distribute trust assets for the minor child’s benefit. The terms of the trust can be tailored to meet the objectives of the trust creator (i.e., owner of the trust assets) and the beneficiary’s needs. Whether the inheritance trust is created under a last will (known as a “testamentary trust) or under a revocable living trust, a trustee will follow the trust instructions and ensure that the terms of the trust areNapping followed. The terms of payout from the retirement plan to the trust is a very income tax complex decision and should be made and ultimately orchestrated with an estate planning attorney, CPA, and financial advisor.
Every asset passing by the contract should have both a primary and contingent beneficiary. If the primary beneficiary dies before the owner, the contingent beneficiary receives the asset on the owner’s death. Identify beneficiaries clearly, using proper legal names and Social Security numbers. Problems occur when the identity is unclear, for instance, when multiple people in a family have the same or similar names.

Why Updating Beneficiaries is as Important as Updating Estate Plan

When an asset is arranged to pass by contract, operation of law, or by non-probate transfer laws, the beneficiary arrangements supersede the control of the owner’s last will or revocable living trust unless the previous will or revocable living trust is itself the beneficiary. Consequently, when the asset owner fails to update the beneficiary arrangement, unintended consequences follow. This can lead to litigation and even family feuds lasting for generations. Beneficiary arrangements must be updated to avoid this problem, especially when there are births, deaths, marriages, and divorces in the family. What was a correct beneficiary for younger children could be a significant headache for adult children.

What Happens When No Beneficiary is Named?

When an asset has no beneficiary designated or no surviving beneficiary, the asset becomes subject to probate. If there is no last will directing the disposition of any assets subject to probate, then the decedent owner has died intestate. As a result, the probate court applies the state laws of intestate succession to determine the beneficiary or beneficiaries of such assets. These laws apply by default andestate planning during divorce presume that people want to leave assets to their relatives based on how closely they are related. However, this is not always what the decedent would have liked.

Suppose no beneficiary is named for a retirement plan or life insurance policy. In that case, the custodian may have a process for assigning a “default” beneficiary, who may not be the person you want.

There may be further tax consequences if no beneficiary is named on tax-deferred retirement accounts.

Family Members with Special Needs Should Not Be Direct Beneficiaries

Means-tested public benefits are subject to strict asset limitations to become or remain eligible. Family members receiving or may become eligible for such uses may not own or have access to assets exceeding those eligibility limits. To preserve access to benefits and to enjoy the benefits of an inheritance, a special needs trust is required to administer the inheritance of the beneficiary with special needs.

The Benefits of Beneficiaries Require Care and Planning

Failing to maintain beneficiary designations is one of the most common and easily avoided errors in estate planning with competent advice. Once an inventory of accounts and assets has been created, an annual update is simple and quick.

We have a Zoom online training session on “Beneficiary Designations for Life Insurance and Retirement Plans” on Monday, June 5, at 6:30 pm. It will cover some basic beneficiary concepts.

To register, you can click here.

Copyright © Integrity Marketing Solutions. All Rights Reserved.

Disability Legal Planning for All Ages

April 10, 2023 No Comments

Find Us Online

Building wealth is only half the job. Protecting wealth for your loved ones and yourself is equally important. Through estate planning, business planning, and asset protection, our firm will help you save everything you love — family, friends, and favorite charities. For more information, be sure to visit our website, where you will have access to our blog, events schedule, and a complimentary newsletter subscription!

Disability Legal Planning for All Ages

A life-altering disability can strike at any time, regardless of your age. From a complicated pregnancy to a severe automobile accident to a cancer diagnosis, these situations can significantly impact your life and the lives of your loved ones. Because one-in-four working-age adultsDNR may become disabled before they retire, there is a chance you may become disabled. Prior legal planning is essential to reduce the legal hardships caused by a debilitating illness or injury. Here are a few tips to help you make proper disability legal plans.

Create Powers of Attorney

If you were disabled due to an injury or illness, which would make your personal, health care, and financial decisions? Would you rather it be someone you know and trust, perhaps a family member or friend, or would you prefer someone appointed for you by a judge who likely knows nothing about you, your family, and your circumstances? If you are like most people, you will choose the former alternative over the latter. Unfortunately, without proper advance legal planning, the latter is the default and more typical result.

Since none of us knows when to expect the unexpected, you need to create a durable power of attorney for health care decisions and a durable power of attorney for financial decisions. The word “durable” means the authority you give the person appointed in your power of attorney will continue in force should you become disabled. After all, that is when you would need them to act for you, right? This is a crucial point to remember.power of attorney

Health Care Matters

Creating a durable power of attorney for health care decisions is a matter of life and death. Who better advocates your health care needs than someone selected by you? Who knows you better than the doctors and nurses treating you? As a result, you should share with your agent the nature of treatments you would want (or not want) under various scenarios.

A health care treatment directive is a document commonly completed with the durable power of attorney for health care decisions. Its purpose is to provide written evidence and guidance regarding end-of-life medical care. Be as general or specific as you wish. While at it, do not forget to include a HIPAA authorization as part of your healthcare disability planning. Under federal law, such approval is necessary for healthcare providers to disclose otherwise confidential and protected information to your agent.

Financial Matters

If the durable power of attorney for financial matters is “general,” then your agent (also known as an “attorney in fact”) may have comprehensive authority to act on your behalf. For example, the agent may be able to sell your home, sign and file your tax returns and pay ongoing bills from your account. On the other hand, if the durable power of attorney is “special or limited,” then your agent will have authority restricted to the acts you specify in the document. The scope of the control you authorize is worthy of careful reflection. There have been cases where agents have exceeded the intended authority.

In addition to controlling the extent of authority you authorize under your general durable power of attorney, you may control when it becomes activated. Suppose you want the source to begin only when you become disabled. In that case, you will want to create a “springing”Medicaid Asset Protection Trust power of attorney requiring some specific proof of your disability defined in the document itself. Otherwise, the authority of your agent may become effective immediately.
Help When It Matters

When disability does strike, and a crisis is at hand, having a trusted, experienced legal team to offer assistance is imperative. That is when the rubber meets the road with your planning. We have been assisting in these critical times since 1995 and are here to help if needed. Please be sure your decision makers know you are connected to a team for just these circumstances.

We have a Zoom online training session on “What to Tell Your Executor” on Thursday, April 20, at 6:00 pm. They may find that introduction helpful.

To register, you can click here.

Copyright © Integrity Marketing Solutions. All Rights Reserved.

Trust Administration Matters

March 14, 2023 No Comments

Find Us Online

Building wealth is only half the job. Protecting wealth for your loved ones and yourself is equally important. Through estate planning, business planning, and asset protection, our firm will help you save everything you love — family, friends, and favorite charities. For more information, visit our website, where you will have access to our blog, events schedule, and a complimentary newsletter subscription!

Trust Administration Matters

If you have never handled funds for another person (as a “Fiduciary”) before, it might feel somewhat daunting to be appointed to serve as the trustee of a trust. In such a role, you owe high loyalty to that person or their beneficiaries if they have died.

This is true whether the trust is created under a will (i.e., a “testamentary trust”) or is an irrevocable trust created under a revocable livingReview your will trust only after the maker of that trust dies.
It is preferable if the person establishing the trust notifies you before your appointment. If they did, you should ask for a copy of the legal document appointing you and ask the preparing attorney to provide you with an overview and address your questions. It is far better to know the responsibilities you will be taking on and politely refuse the appointment now than to bail out when the appointment takes effect later. But first, what are some of those responsibilities?

Trustee 101

A trustee may be a person or a financial institution, or both. The trustee holds legal title to the property for the benefit of another and acts according to the terms of the trust. The trust document will identify who the trustee is. Suppose the person who set up the trust was the initial trustee (as in a revocable living trust). In that case, you might be named successor trustee to administer the trust when the original trustee becomes incapacitated or dies. For example, John might set up a living trust and put all his assets into the trust. He is the initial trustee. John handles all the administrative matters of the trust during his lifetime. When John dies, the person and/or institution appointed as his successor trustee assumes complete control.

If a trust appoints you as the successor trustee, you do not have to do all the work yourself. Handling the assets of another can monopolize your time, so many people hire and supervise specific professionals to do some or all the work. For example, you may have an accountant take care of the taxes. Common Estate Planning scamsAlternatively, the trust may authorize you to appoint an institutional trustee to handle all the “heavy lifting” responsibilities, with you overseeing that trustee.
Trust Administration

The specific actions that a trustee must take require the utmost integrity and care, including the following responsibilities:

  • Read the trust agreement. Make sure you understand what the trust directs you to do. Get professional advice if you have questions. You need to know who the beneficiaries are, what they are supposed to receive, and when you must make distributions to the beneficiaries.
  • Notify the plan’s beneficiaries and provide a basic roadmap to establish reasonable expectations.add a child
  • Marshal the assets. In other words, you must find, secure and value all trust assets as soon as possible. You may be required to file a claim to collect certain assets, like the proceeds of life insurance policies. You may need to hire a professional appraiser to value some assets, like the home’s contents, jewelry, and vehicles.
  • Verify that homeowners insurance and property taxes are current and that coverage will continue until the sale or distribution is made.
  • Identify and pay all final expenses, personal and trust taxes, and legitimate debts of the decedent. Some bills must be paid promptly. You also must provide proper notice to known and likely creditors.
  • Provide an accounting to beneficiaries and obtain waivers or agreements before making significant distributions.
  • Keep track of your time, and find out what fair compensation you deserve for taking on this significant role.
  • Distribute assets. Follow the trust agreement carefully when making distributions to beneficiaries. Be prepared to say “no” to beneficiaries when they demand distributions not authorized by the trust.
  • Terminate the trust. After paying all expenses, debts, and taxes and distributing all trust assets (if the trust permits), you can terminate the trust and conclude your duties as a trustee.

As the trustee, you bear significant potential liability for misdeeds. If the assets are substantial, seek an estate planning lawyer who has been through the process for many years.

To find out more about being a trustee, executor, or as the appointed person in a power of attorney, please join us at a Zoom: Thursday, April 20th, at 6:00 p.m. – “What To Tell Your Backup Person” with Tom Downs.

We also have the following other events available to you or your family, chosen successor agents, and those who you would like to invite to share a learning opportunity:

  • In Person: Wednesday, March 29th, 10:30 a.m. – “Overview of Estate Planning” with Tom Downs, Stephen Wallace, and Justin Wedgewood
  • In Person: Wednesday, April 12th, 5 p.m. – “Overview of Estate Planning” with Stephen Wallace
  • Zoom: Thursday, April 20th, 6 p.m. – “What To Tell Your Backup Person” with Tom Downs

Click here to register.

Copyright © Integrity Marketing Solutions. All Rights Reserved.

Estate Planning Checklist

February 13, 2023 No Comments

Find Us Online

Building wealth is only half the job. Protecting wealth for your loved ones and yourself is equally important. Through estate planning, business planning, and asset protection, our firm will help you protect everything you love — family, friends, and favorite charities. For more information, be sure to visit our website, where you will have access to our blog, events schedule, and a complimentary newsletter subscription!

Estate Planning Checklist

Estate plans, like Rome, are not built in a day. It takes time to map out how you want your estate distributed after death – and decide who will be in charge of your finances and health care in case of incapacity.

An Updated Last Will and Testament

Regardless of the value of your estate, a last will legally distributes assets after death according to your wishes. Your last will should be reviewed every two to three years to reflect changes in your life and changes in the law. Your last will should also be updated when there is a death, divorce, marriage, birth, relocation, or another significant event.Will contest

A revocable living trust is a popular alternative to a last will. If properly prepared and “funded” with your assets, your living trust can avoid probate, unlike a last will. It should likewise be reviewed every two to three years.

It is not uncommon for us to meet with people after death who have no will or one that is terribly out of date. We are working with a case now where the will names a now ex-spouse to manage and receive all.

Review Named Beneficiaries

Any asset with a named beneficiary is distributed outside of your probate estate. For example, perhaps you started a retirement plan (e.g., whether employer-sponsored or your own individual IRA) years ago. Have you forgotten who you designated as the beneficiary at your death? Whoever is designated will inherit the asset. This could be someone who is no longer part of your life or can manage assets. If the designated beneficiary is now deceased, then the retirement plan will become part of your probate estate. It is a prudent practice to regularly review your beneficiary designations for retirement plans and life insurance. Make sure that you also have both primary and contingent beneficiaries.Secondary beneficiary

Failing to have a beneficiary named or deceased beneficiaries named are all too frequent problems we encounter while providing post-death assistance.

Create an Inventory of Assets

Whenever someone dies, they take information when they go. Recreating this information is time-consuming and often imperfect. An inventory of all assets every few years is a necessary act of love. The inventory should include account names and numbers, contact information if the asset was purchased through a financial advisor or broker, the original “basis” of the asset when acquired, and the asset value at the time of the inventory. Passwords to your digital life are also very helpful to pass on.  This information, and other private information, should not be included in your last will. It becomes a public document when filed with the probate court after death.

Our clients have the start of this process in your binder under the personal information tab. Check out how much you have filled in.

Planning for Incapacity

A general durable power of attorney (POA) appoints someone you know and trust to be in charge of your financial life if you are ever incapacitated. This person, known as an agent or an “Attorney-in-fact,” can then legally perform tasks as simple as paying household bills or as complex as selling your home or business. Ask any candidates you are considering whether they are willing and able to serve before committing them to the POA. While you’re at it, always name several alternative backup agents in case the first predeceases you or cannot serve.DNR

As with the POA, a medical or healthcare power of attorney is used to appoint your healthcare agent in the event of incapacity. Your healthcare agent can make your medical decisions, talk with doctors and other healthcare providers, and be involved in your ongoing care. The agent will also talk with your loved ones during critical times. This is ideally someone who can stay clear-headed during emotionally-charged situations.

Have you emailed your documents to the agents? Have they stored them on their smartphones?

End-of-Life Planning

A living will and healthcare treatment directive guides your healthcare agent and loved ones regarding your wishes in the event of a terminal illness or injury when you have little chance of recovery. It clearly states your wishes about being kept alive through artificial means, whether to exhaust all options or to allow you to die.

This document can be difficult to contemplate and should be given careful thought. Not only should it be discussed with your physician, but also with your loved ones. Having these difficult discussions will take the burden from your agent and loved ones, who otherwise would be left to guess about your wishes. In the absence of such planning, too many families fight for control over such decisions in court.

Estate Taxes and Inheritance Taxes

Given the current high federal estate tax exemption of $12.6 million per person, few American households need to be concerned with federal estate taxes for the next year or so. However, some states have their own estate taxes with much lower exemption limits. Maryland’s Estate tax threshold is now Fove Million dollars. Some states have inheritance taxes, which are levied on heirs based on their relationship to the deceased. Maryland taxes people who are not close relatives, like nephews and nieces, 10% on an inheritance of over $1,000. We have both their own estate taxes and inheritance taxes! Consequently, estate tax planning is part of every comprehensive estate plan.

Summary

This brief “checklist” is a good starting point for creating and maintaining your estate plan. As you can see, proper estate planning is not a “set it and forget it” experience. Like your home or automobile, your estate plan requires ongoing maintenance to perform as intended when needed. While thinking about it, take some time to pull out your estate plan and see what might be outdated.

Upcoming Seminar February 22 at 6:00 pm

We have a  Basis Estate Planning Seminar at our office on February 22 at 6: pm. We estimate One hour in length. To register, click here.

This is a discussion about joint ownership, beneficiary designations, wills and how probate works, and living trusts. It is a helpful overview for future financial and medical decision-makers and can be a springboard to introduce your family to your decisions and preferences.

Please join us if you want a refresher on your own planning and want to introduce your family to basic estate planning tools. Also, if you’re going to give a friend a chance to find out about their options for planning, please pass this invitation on to them.

Copyright © Integrity Marketing Solutions. All Rights Reserved.

Our New Lawyer

January 15, 2023 No Comments

Find Us Online

Building wealth is only half the job. Protecting wealth for your loved ones and yourself is equally important. Through estate planning, business planning, and asset protection, our firm will help you protect everything you love — family, friends, and favorite charities. For more information, visit our website, where you can access our blog, events schedule, and complimentary newsletter!

A New Lawyer Has Joined Our Team

We are proud to announce that a new attorney has joined our firm.

Justin Wedgewood is an Estate Planning Attorney who resides in Silver Spring, Maryland. He is blessed to be the father of a beautiful daughter named Emmeline.

Before attending law school, Justin spent five years as a Catholic school educator and parish music and youth minister. His background in education and ministry greatly influences how he approaches law practice.

Justin graduated from Marian University in Indianapolis, Indiana, with a B.A. in Catholic Studies, Pastoral Music Ministry, and Music Performance. He received his J.D. from The Catholic University of America, Columbus School of Law, where he served as a staff editor of the Catholic University Law Review. He is pursuing an LL.M. in Taxation and Certificate in Estate Planning from Georgetown University Law Center.

Justin worked for our firm as a law clerk from June 2021 before being admitted to the bar and has been drafting many of our estate plans for over a year.

In addition to his work as an attorney, Justin serves as a Pastoral Musician at the Cathedral of St. Matthew the Apostle in Washington, D.C., St. Camillus Catholic Church in Silver Spring, Maryland, and St. Philip the Apostle Catholic Church in Camp Springs, Maryland. Justin is also a composer of Catholic liturgical music. His music is published by OCP Publications and is sung in parishes across the country.

A sample of his composition work is located on YouTube here.

Justin is a member of the Maryland State Bar Association and the Catholic Bar Association. Through our firm, he is also affiliated with WealthCounsel and ElderCounsel, national estate planning lawyers networks.

Justin joins our other attorneys, Tom Downs, Stephen Wallace, Patricia Perez, and our dedicated staff of legal assistants.

We are excited to have him join our team.

Upcoming Webinar January 24 at 5:30 pm

We have a short Property Power of Attorney webinar on January 24 at 5:30 pm. We estimate 20 minutes in length. To find out more, click here.

Having a Property Power of Attorney is critical to your estate planning, even if you have a Living Trust, to manage things outside the trust, like retirement plans, litigation, and tax filings.

Please join us if you want a refresher on your planning, and want to introduce your family to the use of a Power of Attorney. Also, if you’re going to give a friend a chance to find out about their options for planning, please pass this newsletter on.

Page1 Page2 Page3 Page4 Page5

(301) 776-7900

Call us Anytime

322 Main Street, Suite 102

Laurel, MD 20707

Powered By

Copyright © IMS. All rights reserved. You may reproduce materials available at this site for your own personal use and for non-commercial distribution. All copies must include this copyright statement. Some artwork provided under license agreement.